Features
Fixed assets
An asset register, depreciation charged a month at a time, and disposals with the gain or loss worked out.
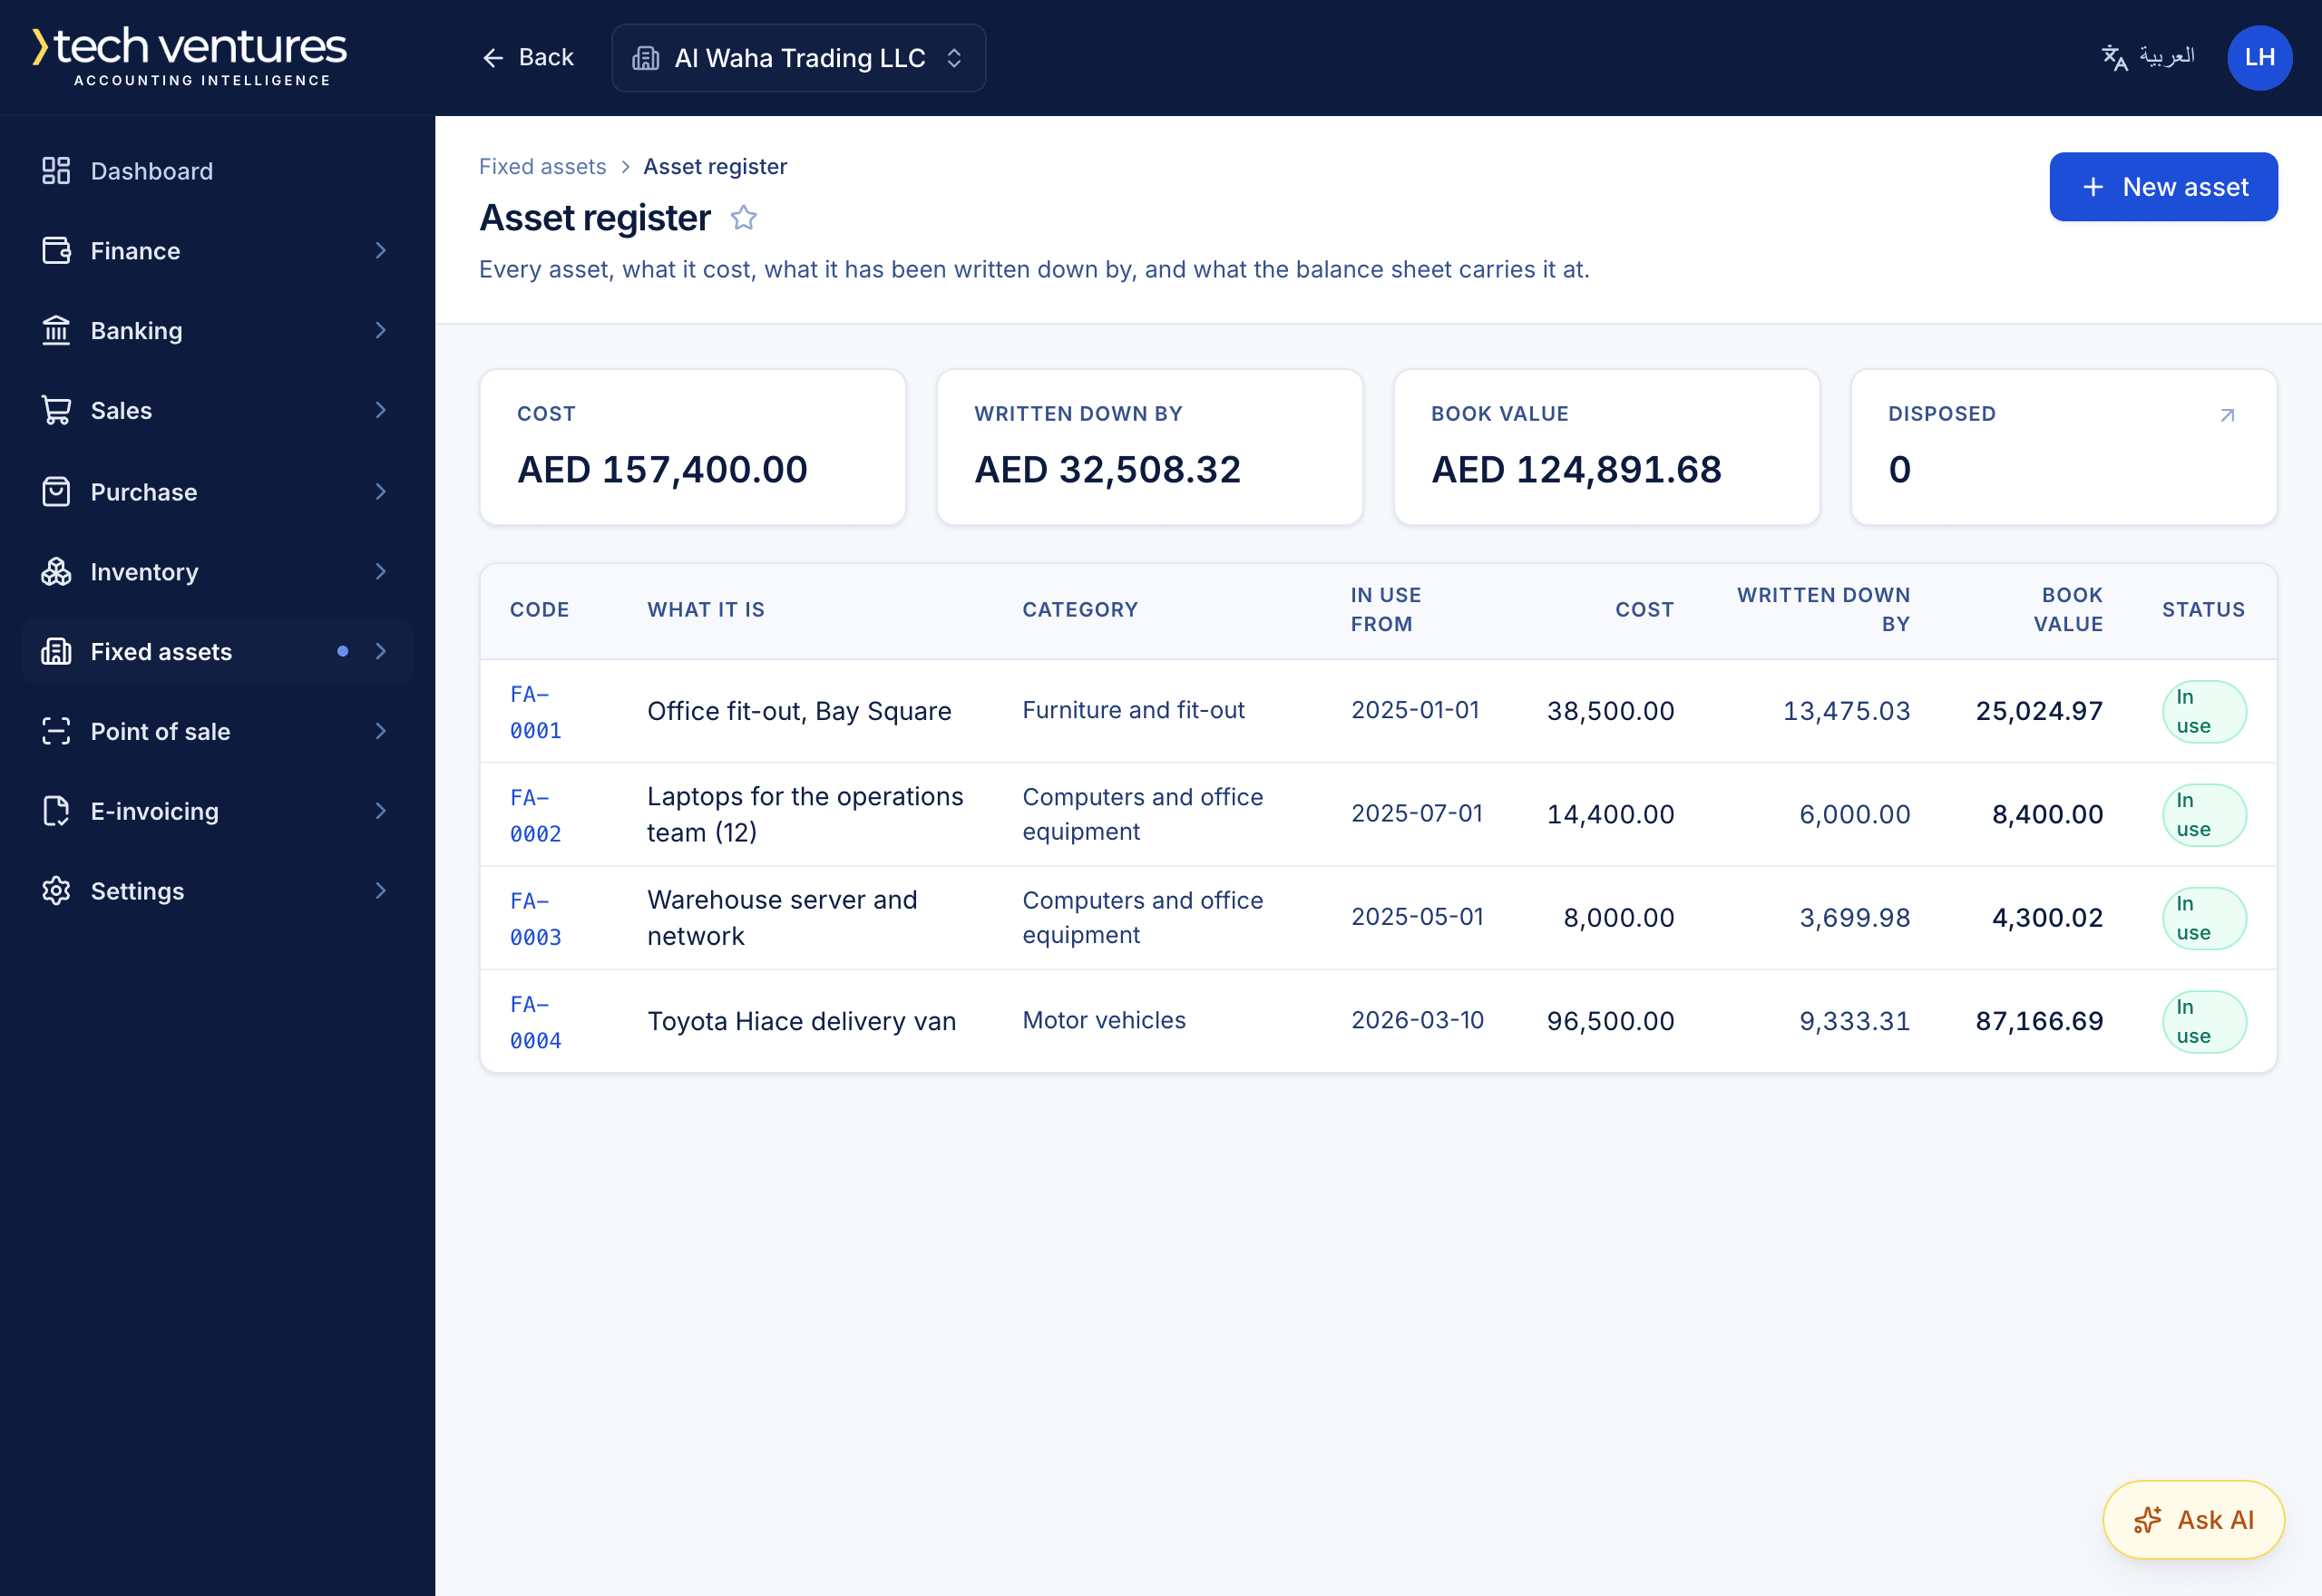
What the company owns and uses — vans, fit-outs, computers — is bought onto an asset account and written down over its useful life. The register says what each asset cost, what it has been written down by and what it is worth now; the ledger carries the same figures because the same entries made them.
In this area
- Asset categories that carry the cost, accumulated depreciation and expense accounts, the method and the useful life, so a new asset needs only what is particular to it.
- Straight line or reducing balance, with a residual value the asset is never written below.
- Depreciation from the month an asset comes into use, which is not always the month it was bought.
- Assets that arrive part-way through their life carry what was already written off, rather than starting again.
- One journal entry a month across every asset in use, with a preview first — and a month can be charged only once.
- Disposal takes out the cost and everything written off it and posts the difference against what was received as a gain or loss.
- Cost centre, project, location and serial number on every asset, and reports of the register and depreciation by asset, category and month.