Features
Purchases and payables
Supplier bills, input VAT, reverse charge, and payments matched to the invoices they settle.
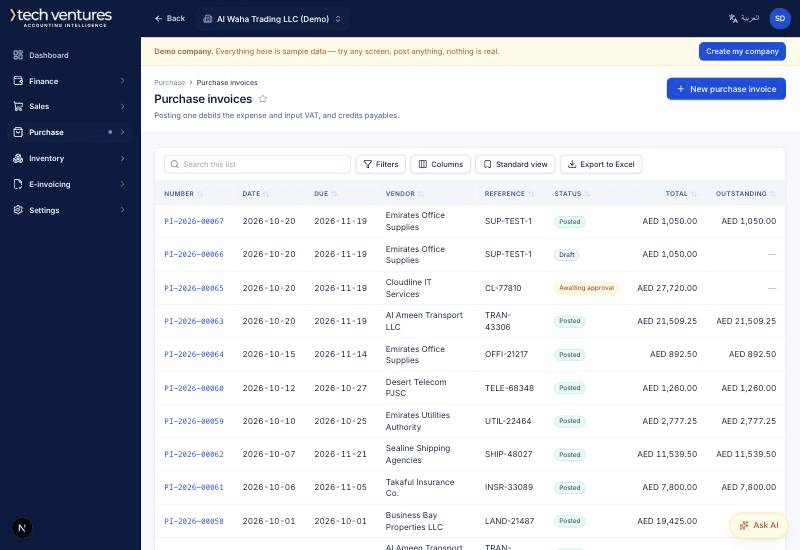
The purchase side mirrors the sales side. A bill credits the supplier and debits an expense — or inventory, if the item is tracked — and the input VAT lands in the account the VAT return reads.
uae-einvoicing.com
In this area
- Purchase orders, bills, credit notes and returns, with the supplier's own number held as the reference the VAT return is evidenced by.
- Tax codes that decide whether input tax is reclaimable: standard-rated, zero-rated, exempt, out of scope, and reverse charge for imported services.
- Reverse charge posted as both halves in the same return, so the net effect is nil and both figures still appear where the FTA expects them.
- Payments allocated against specific bills, with exchange differences posted as a realised gain or loss.
- Vendor groups, vendor ledgers, payables ageing and vendor statements.
- Approval workflows per document type, so a bill over a threshold waits for a second pair of eyes.